Background and Solution
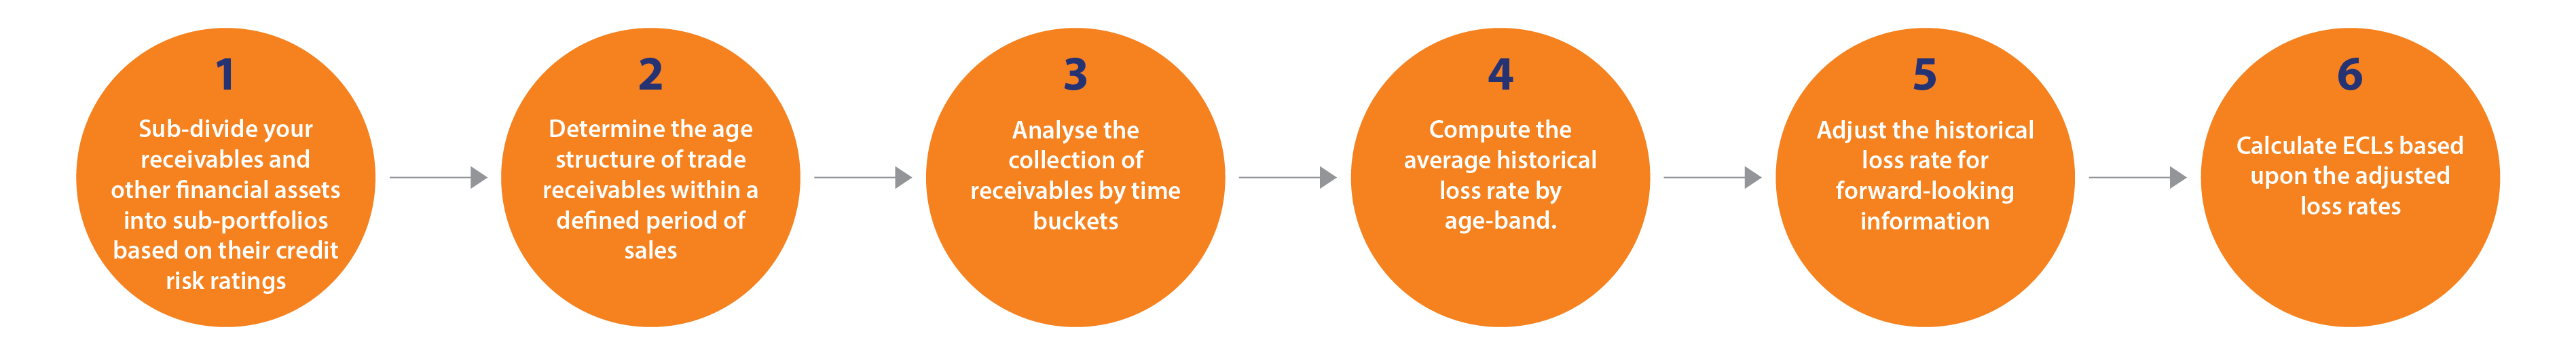
IFRS 9 requires impairments for trade receivables to be calculated on an expected credit loss basis.
- Probability-weighted, without bias to best or worst case scenarios
- Incorporates the effect of time value of money
- Uses historical, current and forward-looking information